Estate planning sounds like something for billionaires and people with complicated families. In reality, almost everyone needs the basics. It’s not just about who gets your stuff — it’s about who makes decisions if you can’t, who inherits what, and how much control you get from beyond the grave.
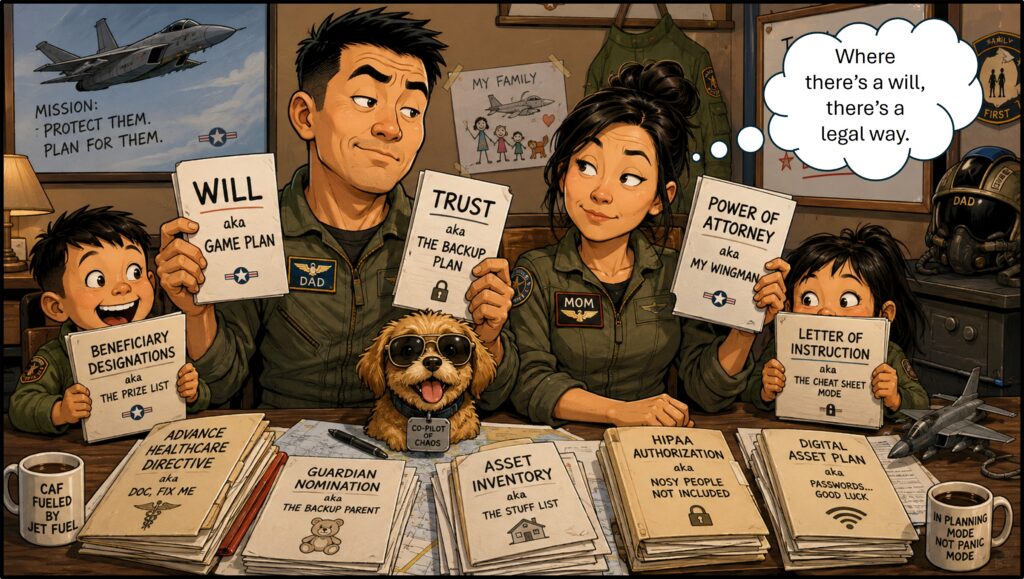
The will is where you start. It names beneficiaries and — critically for parents — says who raises your kids if you’re both gone. But a will doesn’t control everything. Life insurance, TSP, IRAs — those go by beneficiary designation, will or no will. So if your ex-spouse is still listed on your TSP from 2014, your will is not going to save you.
A revocable living trust skips probate and keeps a successor trustee ready to step in if you’re incapacitated. Great for multiple properties, privacy, or detailed instructions on how heirs get their money. It’s not automatically “better” than a will — for plenty of families, a will plus clean beneficiary designations is plenty.
Irrevocable trusts are a different beast: you hand over control on purpose, usually for tax planning, asset protection, or charitable goals. Giving up control sounds bad until it’s the whole point.
A special needs trust protects a disabled beneficiary’s access to means-tested benefits instead of accidentally disqualifying them with a direct inheritance. Get a specialist for this one — the wrong structure can blow up the exact benefits you were trying to protect.
A children’s trust solves a different problem: handing an 18-year-old $400,000 outright isn’t a plan; it’s a hot mess. Staggered distributions at set ages let an inheritance land when your kid is ready for it, not just old enough to legally buy a Cessna.
Charitable trusts are the niche tool — useful if you’ve got appreciated assets and real philanthropic goals, unnecessary for most people.
Then there’s the stuff for while you’re still alive but unable to make decisions: a financial power of attorney and a healthcare power of attorney/directive. Equally important as the will, because estate planning isn’t only about dying — it’s about who can act if you’re incapacitated but still very much breathing.
Military families need extra attention here — TSP, SGLI, pensions, real estate, and moving every two years means beneficiary designations go stale fast. A PCS, marriage, divorce, new kid, or death in the family is your cue to check the paperwork.
The real question isn’t “do I need a trust?” It’s “what problem am I actually solving?” A young family needs a will and guardianship language.
A bigger estate might need trust planning. A disabled beneficiary needs a special needs trust. And nearly everyone needs a plan for who steps in if they can’t make their own decisions anymore.
Estate planning isn’t about preparing to die. It’s about not leaving your family a scavenger hunt.
Fight’s On!
Winged Wealth Management and Financial Planning LLC (WWMFP) is a registered investment advisor offering advisory services in the State of Florida and in other jurisdictions where exempted. Registration does not imply a certain level of skill or training.
This communication is for informational purposes only and is not intended as tax, accounting or legal advice, as an offer or solicitation of an offer to buy or sell, or as an endorsement of any company, security, fund, or other securities or non-securities offering. This communication should not be relied upon as the sole factor in an investment making decision.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any recommendations made will be profitable or equal the performance noted in this publication.
The information herein is provided “AS IS” and without warranties of any kind either express or implied. To the fullest extent permissible pursuant to applicable laws, Winged Wealth Management and Financial Planning (referred to as “WWMFP”) disclaims all warranties, express or implied, including, but not limited to, implied warranties of merchantability, non-infringement, and suitability for a particular purpose.
All opinions and estimates constitute WWMFP’s judgement as of the date of this communication and are subject to change without notice. WWMFP does not warrant that the information will be free from error. The information should not be relied upon for purposes of transacting securities or other investments. Your use of the information is at your sole risk. Under no circumstances shall WWMFP be liable for any direct, indirect, special or consequential damages that result from the use of, or the inability to use, the information provided herein, even if WWMFP or a WWMFP authorized representative has been advised of the possibility of such damages. Information contained herein should not be considered a solicitation to buy, an offer to sell, or a recommendation of any security in any jurisdiction where such offer, solicitation, or recommendation would be unlawful or unauthorized.