There’s a financial planning concept you’ll never find in a Monte Carlo projection: both people in the relationship need to know what’s going on.
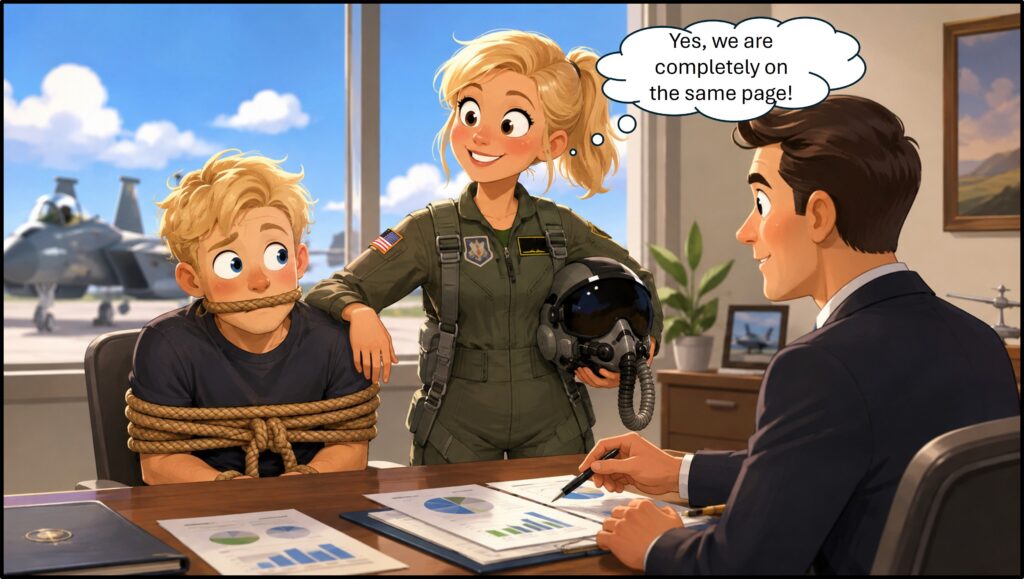
You can have the perfect allocation, airtight insurance, and a beautiful estate plan — but if one spouse is the CFO and the other is basically a hostage at the budget meeting, you have a problem.
You know the dynamic. One person knows every account, password, and TSP allocation down to the percent. The other knows approximately where the credit card lives. Ask “how are we doing financially?” and the CFO pulls up a spreadsheet with 14 tabs. The hostage starts eyeing the exits.
Nobody plans this. One spouse just got more interested in spreadsheets, and efficiency took it from there. The problem isn’t the division of labor. It’s when one person has zero idea how the system works.
Picture a military spouse whose partner deploys — and then they’re the one who gets sick, or is traveling, or is just unreachable. Suddenly someone needs to find the life insurance, access the TSP, and figure out who the advisor is. “Somewhere in the cloud, password involves the dog’s birthday” is not a continuity of operations plan.
Being on the same page doesn’t mean both people become financial experts. Nobody needs two spouses who can calculate a Roth conversion. But both should know the big picture: what you have, what you owe, what happens if one of you dies, and who to call. Above all — what is the money actually for?
Because a real financial plan isn’t a document one spouse nods politely at once a year. It’s a shared roadmap you can both explain.
That doesn’t mean you’ll agree. One of you may think $90K of extra cash flow from a deployment is a lot of extra TSP and IRA savings while the other sees a gleaming new truck as a deployment survival reward. Better to have that fight before the deployment than after.
The goal isn’t identical attitudes about money — it’s understanding each other’s priorities well enough to decide together. Maybe that’s a “conversations required above spending $X” rule. Maybe it’s a monthly 30-minute money meeting. Maybe it’s the CFO staying the CFO while the other spouse handles literally anything else, as long as both understand the whole picture.
The CFO can keep the job. Just don’t let them be the only one who knows where the financial oxygen masks are.
Money stress rarely comes from having too little — it comes from mismatched expectations. One of you thinks you’re saving for retirement; the other thinks it’s a house fund. One thinks the pension means you’re set; the other is quietly panicking about every dentist bill. A spreadsheet won’t fix that. Communication will.
The goal isn’t turning the hostage into a CFO. It’s giving them a financial security clearance — read-in access to the accounts, the plan, the passwords, the professionals, and the right to ask questions without feeling like they’re interrupting a classified briefing.
Financial planning isn’t really about money. It’s about running a life together — and having a plan for when the CFO suddenly goes dark.
Cleared to Rejoin
The best plan isn’t the one with the fanciest spreadsheet. It’s the one where both people know the mission — so if the CFO goes offline, nobody’s standing in the command center asking “uh… where’s the money?”
Fight’s On!
Winged Wealth Management and Financial Planning LLC (WWMFP) is a registered investment advisor offering advisory services in the State of Florida and in other jurisdictions where exempted. Registration does not imply a certain level of skill or training.
This communication is for informational purposes only and is not intended as tax, accounting or legal advice, as an offer or solicitation of an offer to buy or sell, or as an endorsement of any company, security, fund, or other securities or non-securities offering. This communication should not be relied upon as the sole factor in an investment making decision.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any recommendations made will be profitable or equal the performance noted in this publication.
The information herein is provided “AS IS” and without warranties of any kind either express or implied. To the fullest extent permissible pursuant to applicable laws, Winged Wealth Management and Financial Planning (referred to as “WWMFP”) disclaims all warranties, express or implied, including, but not limited to, implied warranties of merchantability, non-infringement, and suitability for a particular purpose.
All opinions and estimates constitute WWMFP’s judgement as of the date of this communication and are subject to change without notice. WWMFP does not warrant that the information will be free from error. The information should not be relied upon for purposes of transacting securities or other investments. Your use of the information is at your sole risk. Under no circumstances shall WWMFP be liable for any direct, indirect, special or consequential damages that result from the use of, or the inability to use, the information provided herein, even if WWMFP or a WWMFP authorized representative has been advised of the possibility of such damages. Information contained herein should not be considered a solicitation to buy, an offer to sell, or a recommendation of any security in any jurisdiction where such offer, solicitation, or recommendation would be unlawful or unauthorized.