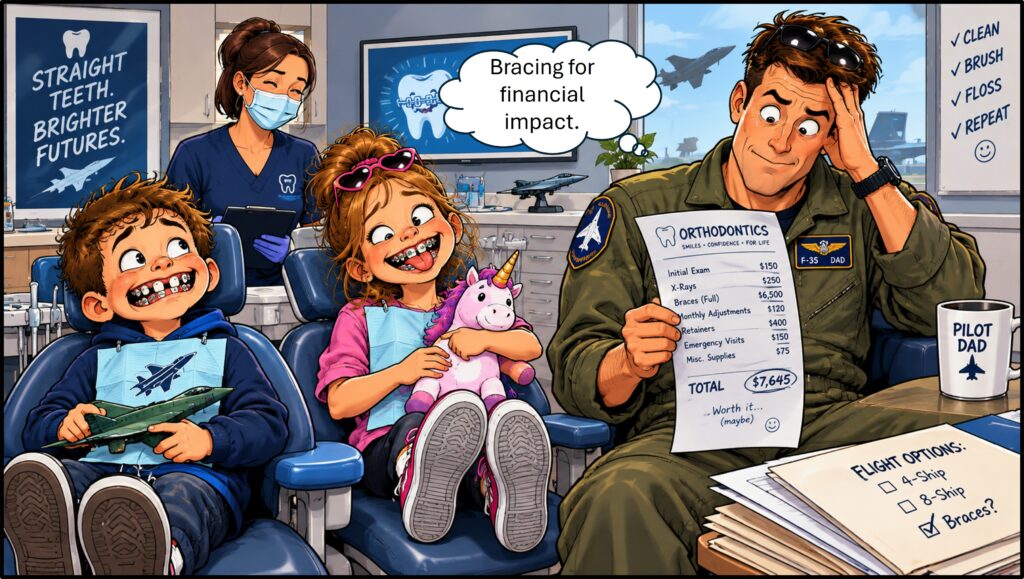
If your child needs braces, you already know the experience can feel like a financial ambush. One minute you’re comparing dental plans during open enrollment, and the next you’re staring at a $6,500 orthodontist estimate, wondering how many combat split dinners during a Vegas TDY that could have funded it, and why orthodontists need to ski Aspen so many times each year.
Braces can be one of the larger healthcare expenses a family takes on, so choosing the right dental plan deserves more thought than simply picking the one with the biggest percentage or highest lifetime maximum.
Dental insurance is particularly good at making things look better on paper than they may be in real life. A plan covering 70% sounds better than one covering 50%. A $3,500 orthodontic maximum sounds better than $2,500. But those numbers don’t tell the whole story.
Network status, negotiated fees, coinsurance, lifetime maximums, and the cost of the insurance itself all matter.
To help demonstrate plan comparisons, let’s look at:
Plan A –
70% orthodontic coverage
$3,500 lifetime orthodontic maximum
$1,600 annual premium
Out-of-network
Versus Plan B –
50% orthodontic coverage
$2,500 lifetime orthodontic maximum
$1,000 annual premium
In-network
At first glance, Plan A looks like the obvious winner. Seventy percent! Higher maximum! Sounds like a big win!
The first step, though, is knowing exactly what “70% Coverage” actually means.
Coinsurance is the percentage of the covered or allowed amount the insurance company pays—not necessarily 70% of the bill sitting in front of you.
An in-network orthodontist has agreed to a negotiated fee with the insurance company. An out-of-network provider may not have that same negotiated rate, meaning the insurance company’s allowance can become an important part of the calculation.
Then there’s the lifetime orthodontic maximum, which puts a ceiling on how much the insurance company will pay.
In other words, the percentage, the allowance, the network, and the maximum all work together.
Let’s Run the Numbers
Suppose the orthodontist quotes $6,500 for braces.
With Plan A, the orthodontist is out-of-network, and the insurance company’s orthodontic allowance is $4,200. The plan pays 70% of that allowance:
$4,200 × 70% = $2,940 insurance payment
You are responsible for:
$6,500 − $2,940 = $3,560
Notice that the $3,500 lifetime maximum never even comes into play. The plan’s allowance limits the benefit before you reach the maximum.
Now look at Plan B. Because the orthodontist is in-network, assume the negotiated fee reduces the cost from $6,500 to $5,400. Plan B pays 50%:
$5,400 × 50% = $2,700
But Plan B has a $2,500 lifetime orthodontic maximum, so the insurance payment is capped at $2,500.
You pay:
$5,400 − $2,500 = $2,900
So despite having the lower coverage percentage and lower lifetime maximum, Plan B saves $660 on the braces themselves.
But we’re not done.
Now add the cost of the insurance over the two years the braces are expected to be in place:
Plan A
Braces out-of-pocket: $3,560
Two years of premiums: $3,200
Total: $6,760
Plan B
Braces out-of-pocket: $2,900
Two years of premiums: $2,000
Total: $4,900
Plan B is $1,860 cheaper overall.
And that’s despite Plan A having the higher coverage percentage, higher lifetime maximum, and seemingly more generous benefit.
The Bigger Lesson
The point isn’t that 50% coverage is always better than 70%, or that in-network is always the right answer. The point is that the biggest number on the benefits chart isn’t necessarily the biggest benefit to your wallet.
When comparing dental plans—especially when braces are involved—look at the whole equation:
Premium + negotiated cost + network status + coinsurance + orthodontic maximum = your actual cost.
Cleared to Rejoin
As if braces were a simple, one-size-fits-all equation. They can be more complicated and stressful than a four-ship upgrade ride.
This is simply an example of getting the gonkulator out and hacking away at the math. Real-life plans will have their own rules, allowances, waiting periods, deductibles, and limitations, so run the numbers using your actual plans and orthodontist.
And this lesson extends beyond dental insurance. Whether you’re comparing health, life, disability, or any other type of insurance, don’t just ask, “What does it cover?”
Also ask, “What will it actually cost me—and what will it actually pay when I need it?”
Fight’s On!
Winged Wealth Management and Financial Planning LLC (WWMFP) is a registered investment advisor offering advisory services in the State of Florida and in other jurisdictions where exempted. Registration does not imply a certain level of skill or training.
This communication is for informational purposes only and is not intended as tax, accounting or legal advice, as an offer or solicitation of an offer to buy or sell, or as an endorsement of any company, security, fund, or other securities or non-securities offering. This communication should not be relied upon as the sole factor in an investment making decision.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any recommendations made will be profitable or equal the performance noted in this publication.
The information herein is provided “AS IS” and without warranties of any kind either express or implied. To the fullest extent permissible pursuant to applicable laws, Winged Wealth Management and Financial Planning (referred to as “WWMFP”) disclaims all warranties, express or implied, including, but not limited to, implied warranties of merchantability, non-infringement, and suitability for a particular purpose.
All opinions and estimates constitute WWMFP’s judgement as of the date of this communication and are subject to change without notice. WWMFP does not warrant that the information will be free from error. The information should not be relied upon for purposes of transacting securities or other investments. Your use of the information is at your sole risk. Under no circumstances shall WWMFP be liable for any direct, indirect, special or consequential damages that result from the use of, or the inability to use, the information provided herein, even if WWMFP or a WWMFP authorized representative has been advised of the possibility of such damages. Information contained herein should not be considered a solicitation to buy, an offer to sell, or a recommendation of any security in any jurisdiction where such offer, solicitation, or recommendation would be unlawful or unauthorized.