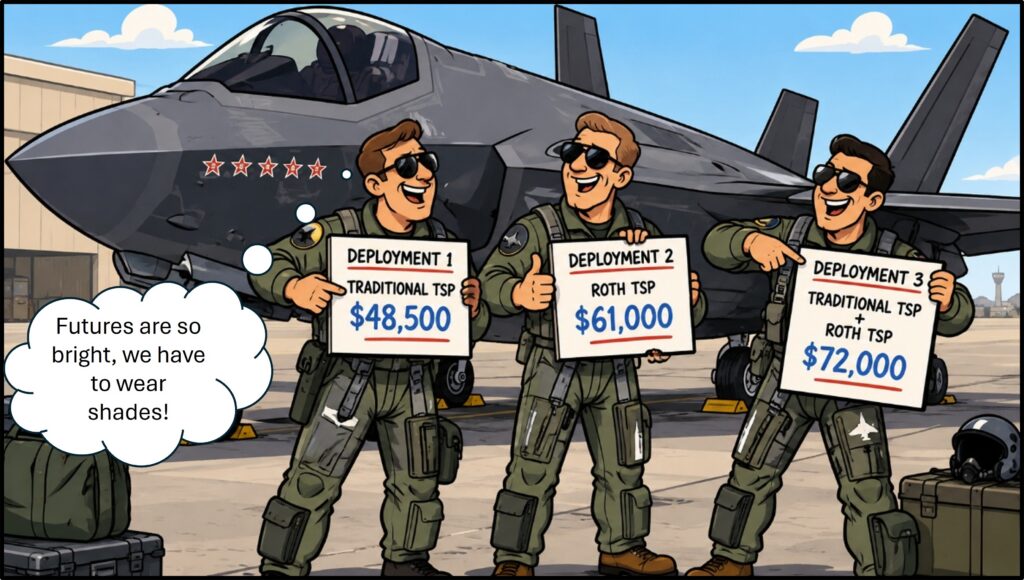
Maxing out the TSP is already a flex. For 2026, the employee deferral limit is $24,500 for anyone under age 50, and the list of folks who do it may be distinguished, but it isn’t terribly long. A combat-zone deployment unlocks some extra stages of afterburner, allowing servicemembers to “super-max” their TSP contributions, saving as much as $72K.
Unfortunately, the list of ways the super-maxing process gets confusing is long and distinguished. Let’s simplify it.
Start With the Two Limits
There are two different ceilings to keep straight.
The first is the normal $24,500 “employee deferral” limit. Roth contributions count toward that limit, as do ordinary pre-tax traditional contributions when you’re not deployed.
The second is the much larger $72,000 “annual additions” limit for 2026. That limit counts nearly everything going into the account, including your own contributions and BRS (blended retirement system) government contributions.
If you’re in BRS, the government can add up to 5% of base pay: a 1% automatic contribution and up to another 4% in matching contributions.
Combat-zone pay creates the opportunity to use the space between $24,500 and $72,000 that you can’t touch in a non-deployed month. Traditional TSP contributions made from tax-exempt combat-zone compensation do not count against the normal $24,500 employee deferral limit, although they do count toward the $72,000 annual additions limit.
Those dollars are tracked as tax-exempt contributions. The contributions themselves have already avoided federal income tax and generally aren’t taxed again when distributed. The investment earnings generated by them, however, are maintained in the tax-deferred part of the TSP and remain taxable unless later moved to Roth (and taxed in a Roth Conversion).
Officers, take note: the combat-zone exclusion for officers is capped at the highest enlisted rate plus hostile fire or imminent danger pay. Traditional contributions attributable to taxable compensation above that amount are regular pre-tax contributions and therefore use part of the $24,500 employee deferral limit.
What a Full-Year Deployment Could Look Like
Assume you spend the entire year in a combat zone and earn $100,000 in base pay.
A $24,500 Roth contribution spread across the year would require 24.5% of $100,000. Because TSP elections use whole percentages, electing 24% would produce $24,000 of Roth contributions.
If you’re receiving the full BRS contribution, another $5,000 goes into the account from Uncle Sam. That puts you at $29,000 toward the $72,000 annual additions limit.
That leaves $43,000 of additional room.
A 43% traditional election on $100,000 of base pay would add another $43,000.
Under these simplified assumptions, the result is $24,000 Roth, $43,000 traditional (tax-exempt), and $5,000 (pre-tax, eventually taxable) from the government: exactly $72,000.
Saving 67% of your own base pay obviously requires both a handlebar mustache and substantial cash-flow capacity, but you’re still reading, aren’t you?
The important point is how the two limits interact. Roth contributions continue to count against the $24,500 employee deferral limit even when the contribution comes from tax-exempt combat-zone pay. Once you reach $24,500, additional Roth contributions aren’t allowed for the year.
But reaching $24,500 does not shut down traditional contributions made from tax-exempt combat-zone compensation. Those can continue until you reach the $72,000 annual additions limit.
That doesn’t mean contribution timing stops mattering. If you’re in BRS, you still want to avoid maxing the normal employee deferral limit, the $24.5K of Roth contributions, so early that you interfere with contributions later in the year and potentially lose part of the government match.
In other words, don’t firewall the Roth in January. Meter it across the year.
Real Deployments Require More Mission Planning
A January-through-December deployment makes for a clean example. Your mileage probably varies.
Suppose instead that you deploy in April and return in the middle of October. Keeping Roth contributions steady throughout the year is good practice in most years anyway. The traditional side requires more attention.
Traditional contributions made before or after the months of combat-zone pay are ordinary pre-tax contributions. Those dollars share the same $24,500 employee deferral limit as Roth contributions. You almost certainly don’t want that to happen.
This creates some notes, warnings, and cautions for an uncertain deployment year.
Don’t turn on the traditional contribution too early. If you increase traditional contributions in March and the deployment doesn’t begin until May, those March dollars are taxable traditional contributions. You’ve now used part of the $24,500 limit and reduced the room available for Roth contributions.
Allow for payroll processing time. You should make your pay and TSP changes by the 15th of the month prior to the month you want the change. E.g., 15 March for a 1 April effective date.
Pick a target that fits your actual goals. There is no requirement to hit $72,000. You may decide that contributing an additional $10,000 or $20,000 during the deployment is enough. Determine the amount first, translate it into a contribution percentage, and use that rate during months in which the pay qualifies for combat-zone treatment.
Manage the return home carefully. If you leave the combat zone in mid-October, October still qualifies as a combat-zone month for purposes of the exclusion. Once the return date becomes reliable, reduce the traditional election so that taxable contributions in later months don’t unexpectedly consume your remaining $24,500 deferral room.
The real planning risk isn’t that you’ll somehow lose access to the TSP entirely. It’s using too much of the $24,500 employee deferral limit on pre-tax traditional contributions outside the deployment window. That can reduce the amount available for Roth contributions and make the BRS match harder to manage.
Deployment dates move. Contribution percentages should move with them.
Guard and Reserve Members Have Another Limit to Watch
For Guard and Reserve members with civilian employment, there’s an additional wrinkle.
The $24,500 employee deferral limit applies to you across plans, not separately to every employer. Contributions to a civilian 401(k), 403(b), or another TSP account can therefore consume part of the same annual limit.
If you’re trying to super-max during a deployment while also funding a civilian retirement plan, this is one of the easiest places for the numbers to get complicated.
Roth Conversions- the Bonus Plan
Beginning in 2026, the TSP permits in-plan Roth conversions.
That can be especially relevant during a combat-zone year because your taxable income may be unusually low. A conversion pays tax at today’s rate to convert traditional TSP money into Roth money (usually never taxed again).
It’s possible, but rare, for steely-eyed killers to have a higher tax rate in retirement than during a deployment year. You’ll need both an abacus and a crystal ball to be sure.
You Can’t Simply Convert Only the Tax-Exempt Dollars
The “pro-rata rule” matters. It states that when you do a Roth Conversion, whether inside the TSP or a Traditional IRA, the conversion is always a pro-rata mix of the pre-tax and after-tax (tax-exempt) dollars. You can’t only convert the pre-tax dollars inside the TSP.
Assume your TSP contains:
- $100,000 of Roth money
- $100,000 of pre-tax traditional money
- $100,000 of tax-exempt combat-zone contributions
The existing $100,000 Roth balance has nothing to do with the conversion calculation because the conversion is coming from the traditional side of the account.
That traditional side totals $200,000 and, in this example, is split evenly between pre-tax money and tax-exempt contributions.
Ignoring the TSP’s required source minimums for the moment, a $20,000 conversion would therefore generally consist of about $10,000 of pre-tax traditional money and $10,000 of tax-exempt traditional contributions.
The $10,000 pre-tax portion would be taxable. The $10,000 representing tax-exempt contributions would not.
If your account contains a large amount of pre-tax money, a conversion can still generate a substantial tax bill. That’s a situation where professional tax help may be worthwhile.
Younger Service Members May Have an Unusual Opportunity
Someone who has contributed primarily to Roth TSP throughout a relatively short career may not have accumulated much pre-tax money.
A portion of the traditional balance may simply be BRS government contributions, since automatic and matching contributions currently go into the traditional side of the TSP.
Combine a relatively small pre-tax balance with unusually low taxable income during a deployment, and a Roth conversion may occur at lifetime low tax rates.
In the right situation, a younger service member could return from deployment with a TSP that is nearly-all Roth by performing in-plan conversions every pay period.
There is one operational limitation. Active participants generally must leave at least $500 in each applicable non-Roth payroll source, including tax-deferred employee contributions, tax-exempt employee contributions, automatic 1% contributions, and matching contributions.
So, while you’re still actively contributing through payroll, you may not be able to convert every last traditional dollar.
Cleared to Rejoin
You can super-max your TSP with as much as $72,000 (2026), but measure twice with your Roth and Traditional percentages and timing.
The key is understanding that the $24,500 employee deferral limit and the $72,000 annual additions limit are different limits serving different purposes. Combat-zone traditional contributions t allow you to operate in the space between them.
Don’t skip the opportunity just because $72K feels unrealistic. If the deployment simply gives you the cash flow to max the normal $24,500 limit for the first time, you still get a gold star.
Finally, even if you don’t super-max your TSP, take a look at in-plan Roth conversions to see if they might lower your lifetime tax bill.
Fight’s On!
Winged Wealth Management and Financial Planning LLC (WWMFP) is a registered investment advisor offering advisory services in the State of Florida and in other jurisdictions where exempted. Registration does not imply a certain level of skill or training.
This communication is for informational purposes only and is not intended as tax, accounting or legal advice, as an offer or solicitation of an offer to buy or sell, or as an endorsement of any company, security, fund, or other securities or non-securities offering. This communication should not be relied upon as the sole factor in an investment making decision.
Past performance is no indication of future results. Investment in securities involves significant risk and has the potential for partial or complete loss of funds invested. It should not be assumed that any recommendations made will be profitable or equal the performance noted in this publication.
The information herein is provided “AS IS” and without warranties of any kind either express or implied. To the fullest extent permissible pursuant to applicable laws, Winged Wealth Management and Financial Planning (referred to as “WWMFP”) disclaims all warranties, express or implied, including, but not limited to, implied warranties of merchantability, non-infringement, and suitability for a particular purpose.
All opinions and estimates constitute WWMFP’s judgement as of the date of this communication and are subject to change without notice. WWMFP does not warrant that the information will be free from error. The information should not be relied upon for purposes of transacting securities or other investments. Your use of the information is at your sole risk. Under no circumstances shall WWMFP be liable for any direct, indirect, special or consequential damages that result from the use of, or the inability to use, the information provided herein, even if WWMFP or a WWMFP authorized representative has been advised of the possibility of such damages. Information contained herein should not be considered a solicitation to buy, an offer to sell, or a recommendation of any security in any jurisdiction where such offer, solicitation, or recommendation would be unlawful or unauthorized.